She declared Rs 43,796 income but omitted Rs 14.02 lakh interest from her ITR; tax officer imposed a 200% penalty of Rs 4.85 lakh, but ITAT cut it to Rs 1.21 lakh
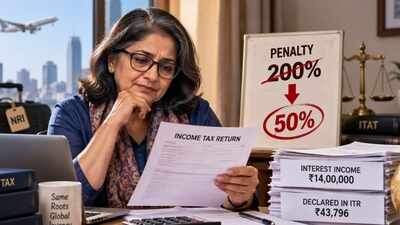
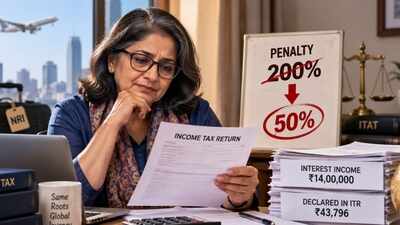
You file your income tax return but end up under-reporting your income. But, the Income Tax Department treats it as mis-reporting of income and imposes a heavy penalty on you. What happens then?This is the case of a 57-year old non-resident Indian (NRI) woman who ended up under-reporting her income when she filed her Income Tax Return, and the gap was huge.
What the case is about
The NRI woman declared an income of Rs 43,796 for the assessment year 2020-21. But the Income Tax Department tracked an interest income of Rs 14,46,321 that was not disclosed in her return and imposed a 200% penalty on her.The Assessing Officer treated the omission as misreporting and imposed a penalty of Rs 4.85 lakh, equivalent to 200% of the tax payable on the under-reported income.The additional interest income was brought to tax during reassessment because it had not been disclosed in the original return. The tax officer classified the omission as misreporting, which attracts a penalty of 200% under Section 270A, rather than the 50% penalty applicable to ordinary under-reporting.The woman denied deliberately concealing income. In her appeal, she said she had consistently filed her returns on time and had never intentionally under-reported her income.The CIT(A) upheld the penalty, observing that interest income of Rs 14,02,525 had been completely omitted from the return..The CIT(A) found that the interest income of Rs 14,02,525 had been entirely left out of the return. It also noted that the taxpayer had not voluntarily disclosed the income or provided an explanation and supporting documents despite receiving several notices.The taxpayer then approached the Income Tax Appellate Tribunal (ITAT), Mumbai, which upheld the penalty for under-reporting but reduced the applicable penalty rate from 200% to 50%
How did she explain the mismatch?
Her advocate said the woman was living abroad, had limited technological knowledge and had handed over her tax compliance to an accountant. She therefore remained unaware of the electronic notices issued by the department. After learning about the discrepancy, she paid the additional tax and interest.“She was only informed about the additional tax liability of Rs 2,42,589 plus interest amounting to Rs 3,06,821, totalling to Rs 5,49,410, which was paid on January 23, 2025, as the said tax plus interest liability had risen due to the accountant’s mistake.”The taxpayer argued that the case involved under-reporting rather than misreporting and that the penalty should therefore have been 50% of the tax liability, or Rs 1,21,295.The woman maintained that she was an NRI during the relevant period and remained so until April 1, 2025. She attributed the omission to the accountant handling her tax compliance and her lack of awareness of the electronic notices.
What did ITAT Mumbai say?
The tribunal found that omission of income cannot automatically be classified as misreporting. It considered the taxpayer’s circumstances and the fact that she paid around Rs 5 lakh in tax and interest after becoming aware of the discrepancy.“In our considered view, non-compliance with electronic notices in these peculiar circumstances cannot by itself establish that the original omission of interest income represented deliberate misreporting warranting penalty at 200%,” it said.The tribunal also stressed that the law makes a distinction between ordinary under-reporting, which attracts a 50% penalty, and under-reporting resulting from misreporting, which attracts 200%.“The higher rate cannot be applied merely because the Department detected the omitted income or because the assessee did not respond to notices.”ITAT Mumbai therefore sustained the penalty under Section 270A for under-reporting, but directed the Assessing Officer to apply the 50% rate instead of 200%.Anuj Dave, Practice Head (Ahmedabad & Mumbai) at Clavius Legal told ET that several circumstances taken together supported the taxpayer’s case. “She was a non-resident living abroad, had entrusted her compliance to an accountant, claimed limited technological knowledge and to have been unaware of the electronic notices, and paid tax and interest of Rs 5,49,410 on becoming aware of the liability.”It is important to note that the Rs 5,49,410 already paid towards tax and interest does not cancel the separate penalty liability.The payment of tax and interest was considered in the taxpayer’s favour, but did not serve as a defence against the penalty.The original penalty was Rs 4,85,178 at the 200% rate. That rate has now been reduced to 50%, but the taxpayer will still have an additional penalty liability, Mathews said.What’s important to note is that an addition to income during assessment or reassessment does not, by itself, establish misreporting. The Revenue must show that the facts fall within one of the specified categories.Similarly, failure to respond to statutory notices can be relevant, but does not by itself prove deliberate misreporting.